Could Putting a Gye (Korean Savings Club) on a Blockchain Stop the Organizer From Vanishing With the Money?
Would putting gye money on a blockchain record book stop organizers from vanishing?
Everyone sees where the money goes, but it can't stop people who don't pay
Members pay in
Everyone sees who paid
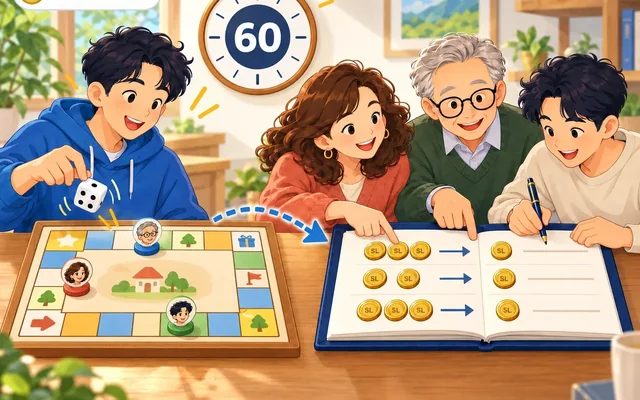
A promise program holds it
Turns and rules written in advance
Paid to this month's turn
Skips the organizer's account
Next month's payment
If unpaid, the book can't force it
A gye (계) is a Korean savings club: members pay a set amount each month and take turns getting the whole pot, and an organizer (계주) collects the money. Putting it on a blockchain can cut down the problem of the money and the ledger all piling up with that one organizer. But a blockchain can't stop a member from not paying and dropping out.
Do gye collapses still happen?
Yes. According to a News1 article on February 2, 2026, Dongnae Police Station in Busan, Korea is investigating a gye organizer in their 60s for fraud and embezzlement. This gye had run for more than 15 years, and payouts stopped in April 2025. The victims were estimated at 30-odd to 100-odd people, and the losses at anywhere from several billion KRW (Korean won) to around 20 billion KRW.
An Edaily article on May 5, 2023 covers a case of around 4 billion KRW in a fishing village in Gyeongju, North Gyeongsang Province. About 40 victims had been handing the organizer 1 million to 2 million KRW every month, starting over 20 years earlier. Police said they believed the organizer spent the gye money freely, paid earlier members with later members' money, and then disappeared.
Getting the money back or getting a conviction isn't easy either. In a Seoul case in a LawTalk News article on May 22, 2026, the losses came to 6 billion KRW, but the amount sent to prosecutors was about 300 million KRW. That's because fraud means proving the person had no intention or ability to pay back from the moment they took the money.
In all three cases, the gye money all went to the one organizer.
What changes with a blockchain record book?
A blockchain (a record book that many people hold together) is like every gye member holding their own copy of the gye ledger. If one person edits only their copy, it won't match the others and shows up right away. A record, once written, is hard to change later, and anyone can check it on their phone.
On top of that, you add a smart contract (a program that moves money on its own, following promises written in advance). You write the rules down at the start, like "10 people, 100,000 KRW a month each, in order from No. 1 to No. 10." Then the pooled money goes straight to that month's turn without passing through the organizer's bank account.
Has anyone actually tried it?
Abroad, yes. On February 22, 2017, the US company WeTrust announced on its blog that it had released the first trial version of a group where members take turns getting a lump sum (called a ROSCA in English, similar to Korea's gye) on the Ethereum blockchain. To use it, you needed an Ethereum coin wallet and, separately, a browser that could handle that wallet (for example, the MetaMask extension).
The gye program code the company published shows that the turn order can be chosen from "whoever bids to take the least," "random," or "a set order." Someone who takes the lump sum without having paid in fully is blocked from withdrawing until they make up what they owe (or until the gye ends). If the program doesn't hold enough money, it leaves a record saying "couldn't pay in full."
The code also has an emergency switch. If a serious flaw is found, the WeTrust account unlocks the switch, and if the gye operator triggers it, the operator takes out all the money and hands it out outside the record book. The gye program code (ROSCA.sol) was last changed on January 9, 2018. The last change pushed to the repository was on April 30, 2019, and it only touched a settings file. On September 29, 2026, the company's website and service address wouldn't open. I couldn't find an official shutdown announcement.
A sponsored post on the website of Nigerian broadcaster Channels TV (July 28, 2021) introduced, in the company's own words, Xend Finance, a blockchain service for esusu (a West African group where members take turns getting a lump sum) that only let you withdraw what you'd put in after everyone else had been paid.
In Korea, a company planned to launch an app that didn't use a blockchain. On June 12, 2019, Korea's Financial Services Commission designated KONA I's gye service as an innovative financial service in Korea (a program that loosens rules for a while so something can be tested). Members would send money directly to that month's turn, and the record would be shared with the other members. It was said to be launching in November 2019. It's an example of trying to make "a record everyone sees" without a blockchain. I couldn't confirm from public sources whether it actually launched or how much it was used.
What can't a blockchain fix?
It can't stop people who don't pay. The ledger only shows everyone "didn't pay." If someone who took the lump sum early drops out, the people later in line lose out. Locking the money up for a long time, like the esusu service, shrinks this hole, but it also shrinks what's good about a gye: getting to use a lump sum early.
If what's written in at the start is wrong, it stays wrong. Whether a wallet address really belongs to that member has to be checked outside the ledger. The code can have flaws too, which is why WeTrust added a separate emergency switch that the operator side turns on.
There are legal issues too. According to a Financial News (News1, June 12, 2019) article, KONA I applied for a special exemption so an app where individuals pass gye money to each other wouldn't be blocked by Korea's Money Lending Business Act (such as having to register as a loan broker). The Financial Services Commission allowed it within limits: for 2 years, up to 2,000 users, and up to 500,000 KRW per person a month. I couldn't confirm in this post which laws apply if you collect gye money in coins. Getting the money back after something goes wrong is still up to the police and the courts.
What kind of blockchain SASEUL (also known as SASEUL coin) is, is in SASEUL basic facts, and who writes the transaction record book and how is in SASEUL has two record books?.
Sources
- News1 (Nate News) · "부산서 최대 200억 곗돈 사기 고소장 접수…60대 계주 수사" ("Complaint filed over gye fraud of up to 20 billion won in Busan... organizer in their 60s investigated") · 2026-02-02, checked 2026-09-29
- Edaily · "'40억 곗돈 들고 잠적'..조용한 경주 어촌 마을 발칵 뒤집혀" ("'Vanished with 4 billion won in gye money'... quiet Gyeongju fishing village in uproar") · 2023-05-05, checked 2026-09-29
- LawTalk News · "8년간 60억 곗돈 사기, 3억만 송치… 검찰, '돌려막기' 입증해 혐의 확대할까?" ("6 billion won gye fraud over 8 years, only 300 million referred... will prosecutors widen the charges by proving money was shuffled between members?") · 2026-05-22, checked 2026-09-29
- WeTrust Blog (Medium) · WeTrust's First Product is Live on the Mainnet · 2017-02-22, checked 2026-09-29
- WeTrust Blog (Medium) · WeTrust Community Update, August 14 2017 · 2017-08-14, checked 2026-09-29 (full app aimed for the end of that year)
- WeTrust public code · rosca-contracts / ROSCA.sol · last changed 2018-01-09 (ROSCA.sol), last repository commit 2019-04-30, checked 2026-09-29 (three ways to set the turn order, blocking withdrawals by people behind on payments, emergency switch)
- Channels TV · Esusu Goes Digital, Introduces Xend Finance Platform · 2021-07-28, checked 2026-09-29 (marked as sponsored, the company's own description)
- KDI Economic Information and Education Center · '19.6.12일 금융위원회, 혁신금융서비스 6건 지정 (금융위원회 자료) (June 12, 2019: Financial Services Commission designates 6 innovative financial services, FSC material) · 2019-06-12, checked 2026-09-29
- Financial News (News1) · "계모임 운영하는 모바일 앱 나온다…선불전자지급수단 활용" ("A mobile app for running a gye is coming... using prepaid electronic payment") · 2019-06-12, checked 2026-09-29 (Money Lending Business Act exemption, usage limits)
- Hankook Ilbo · "곗돈, 온라인으로 투명하게 관리하세요" ("Manage your gye money transparently online") · 2019-06-12, checked 2026-09-29 (how the transfer history is shared)
- Official SASEUL explorer · Statistics · checked 2026-09-29 13:21 (2,326,751 mining record pages, first record 2022-05-17 04:49, 9 validator seats)
- CoinMarketCap · About SASEUL · the project's own description, checked 2026-09-29 (6 of 9 seats sign)
I opened and checked 3 news articles, 2 WeTrust blog posts and its public code, the Channels TV sponsored post, the Financial Services Commission material and 2 articles about it, and SASEUL's official explorer and the CoinMarketCap description myself on September 29, 2026.